
Reading Today's Betting Predictions Without Buying the Hype
 Available in US
A search for “best bet prediction for today” usually ends in one of two places: a tipster promising a winner, or a list of free picks dressed up as analysis. This page is neither. It treats the question seriously rather than literally — what makes a tip stand up at all, what separates a price from a prediction, and what today’s offers actually cost the bettor who claims them. The marketing around daily tips leans on certainty the math never provides, and the sharpest move a bettor can make is to recognise that before staking anything.
Data current as of 26 October 2026 and verified against the public register of the Gambling Commission.
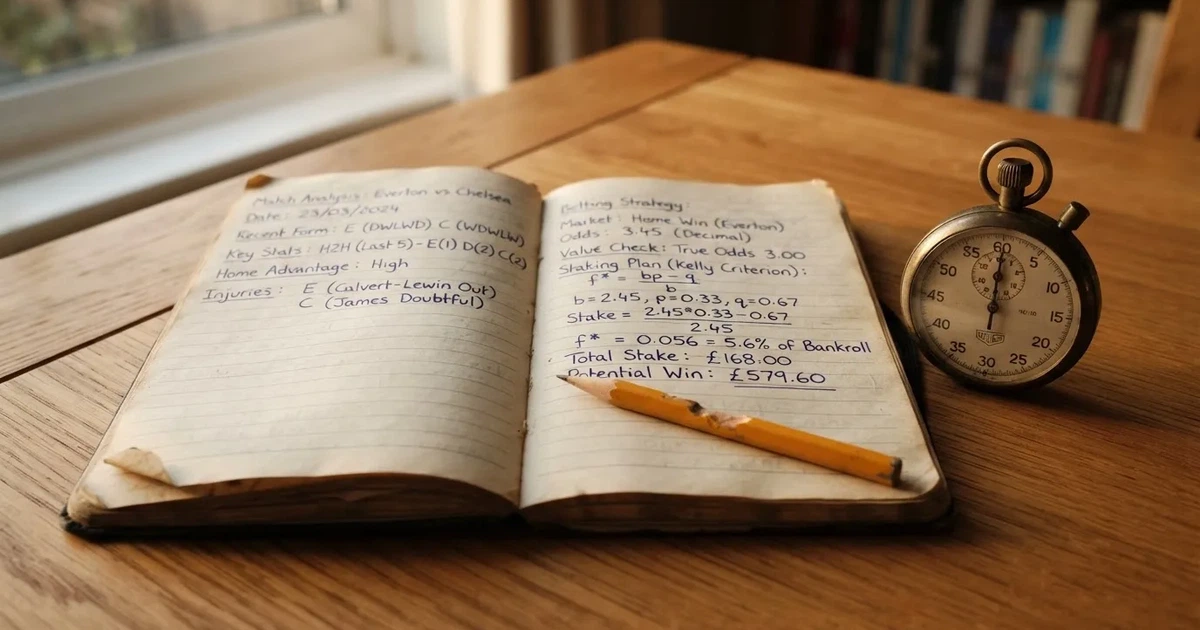
The phrasing “best bet” carries a false promise. A book cannot know which selection wins today’s card, and any outlet that claims it does is selling confidence rather than information. What tipsters, model builders and serious bettors actually produce is a *probabilistic view* of the event — a stake-weighted estimate of how likely each outcome is — and the question is whether the price on offer sits above that estimate once the bookmaker’s margin is removed. That single difference, price minus true probability, is what “value” means in the betting vocabulary, and it is the only honest reading of “best bet” that survives contact with the mathematics.
The bookmaker’s margin lives inside every odds line the reader sees. It is the reason six outcomes at “evens” never return what the bettor thinks, and it is the reason a free bet with a 10x wagering requirement quietly hands back less than a worker earning minimum wage. The angle here is cost — what each prediction, price and offer actually costs the person paying for it. That angle runs through the licensing frame, the responsible-gambling frame, the mobile and app frame, the strategy and staking frame, the ten-bookmaker comparison and the overview that closes the page.
The plan below follows that order. It opens with legality and player protection, because no bet is well-priced if the operator is unverified or the customer’s losses are running without a guardrail. It moves to mobile, where most of today’s bets actually happen. Then strategy, where the “prediction” question is properly answered; the ten-bookmaker frame; and finally an overview that names what the reader walks away with.
Where today’s prediction sits inside the law
A bookmaker serving customers in Great Britain needs a Gambling Commission licence wherever the operator itself is based. The Gambling (Licensing and Advertising) Act 2014 closed that off: a Curaçao, Maltese or Gibraltar registration is not a substitute, and any brand accepting a bet from a reader in England, Scotland or Wales without a Commission licence is breaking section 33 of the Gambling Act 2005. The Commission’s public register is the whole test — searchable by business name, trading name, domain or account number — and the account number on the operator’s own page should match what the register shows. Northern Ireland sits outside the Act and under its own older law, so a “GB-licensed” tag is a Great Britain claim, not a UK-wide one.
Each licence carries a category. The category that covers ordinary sports betting on real events is *remote general betting standard (real events)* — the line most readers will see if they look up a brand themselves. Pool betting, virtual events, exchange operation and pool betting each run under their own category. The minimum age is 18, and identity, address and date of birth are verified before any deposit — including for a free bet or bonus offer, after the rule came into force on 7 May 2019. Anonymous play does not exist on a licensed site, and that has consequences for the small number of bettors who want to stay anonymous for legitimate reasons.
Financial spread betting is the exception. Where the product is a spread bet on a financial index or share, the Financial Conduct Authority is the regulator, not the Gambling Commission — Spreadex carries that exact carve-out, with the firm’s own page making clear that financial spread-betting losses can exceed the deposit. The two regimes read very differently: a financial spread bet is a leveraged position with margin calls, and a sports spread bet is a stake-based product on a sports outcome. They share the word but not the risk.
The off-shore frame matters because some readers land on unlicensed sites through affiliate links. The honest framing is loss of protection, not legality — a customer who simply bets on an unlicensed site is not committing a listed offence, but the protections that come with a GB licence vanish: no GAMSTOP coverage, no Commission complaints route, no approved dispute-resolution body, and no British consumer redress if the operator withholds funds. The licensed side brings verification, deposit limits, the 10x wagering cap and the £150 financial vulnerability threshold, and those are visible constraints on the bettor’s freedom. The unlicensed side brings none of them, and funds sit with a firm that has no British accountability. Neither is “the safe choice” by default — the question is which trade-off the reader is willing to make.
For most readers of a UK-licensed comparison, the regulatory fact is the licence number in front of them, not a long reading of statutes. The licence is what is being purchased when an offer is claimed; it is what makes the complaints route exist; and it is what binds the operator under the consumer-protection layer the next section sets out.
What “safer gambling” actually obliges a licensed operator to do
Safer-gambling language can read as window dressing on a marketing page. The licensed side is narrower and more specific: a set of duties the operator must meet under the Licence Conditions and Codes of Practice (LCCP), with the Commission’s enforcement behind it. The reader does not see the rules when they place a bet — they appear the moment a feature is invoked or an offer is claimed, often in ways the reader does not connect to the regulation that produced them.
GAMSTOP is the centrepiece. The national multi-operator online self-exclusion scheme has been a mandatory licence condition for online operators since 31 March 2020, and every brand reviewed on this page runs under it. A self-exclusion can be set for six months, one year, five years or five years with auto-renewal, and after the minimum period the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. What GAMSTOP does is block the customer from any GB-licensed online bookmaker for the chosen period — the operator side is bound to refuse registrations and bets from a self-excluded customer. It does not cover betting shops, which sit under a separate in-premises service, and it does not cover unlicensed sites. A reader who has self-excluded and still finds a way to an unlicensed operator has not defeated GAMSTOP — the operator has simply chosen not to join it.
The financial vulnerability check is the newest layer. Under LCCP condition 3.4.4, in force since 30 August 2024 and applied since 28 February 2025, licensed remote operators run a public-record check on a customer whose deposits minus withdrawals cross £150 in a rolling 30-day window. The check looks at registers such as bankruptcy orders and county court judgments — it is not an income check and not a credit-reference check. The £150 figure is published and fixed, not a per-operator threshold. The check exists so the operator can identify customers whose financial picture puts them at higher risk and apply protective steps the LCCP lists: a deposit limit, an interaction pause, a referral. It is not a punitive mechanism — it is an interrupt before losses grow.
The “affordability checks” headline is broader than the rules actually in force. The Commission has set out a staged plan for fuller financial risk assessments, announced in July 2026 with no start date. Until that plan has a date, the only financial check live is the public-record vulnerability check above, and any extension that demands payslips, bank statements or proof of income is not yet in force. State that as “announced, staged, no start date” rather than as an active obligation, because a customer who claims a deep income check exists will be looking for a rule that does not yet bind the operator.
Deposit limits are the customer’s lever, not the state’s. Remote Technical Standard 12 obliges the operator to offer a gross deposit limit on a fixed time frame, with changes since 31 October 2025 and a second phase pushed back to 30 September 2026. There is no state-set deposit ceiling and no state-set loss ceiling for sports betting: the limit is what the customer chooses, and the operator is required to let the customer set and lower it quickly. The state-set numbers that do exist apply to the operator’s conduct, not the customer’s stake — a remote bookmaker must offer the limit; nothing stops the operator from setting lower ones. A reader can also impose a stake limit on the account through responsible-gambling settings, where available.
The promotion rules in force since 19 January 2026 reshape what “bonus” actually means. Wagering requirements on bonuses are capped at 10x — a £10 bonus at 50x wagering needs £500 of qualifying bets, and the cap forbids any bonus whose turnover requirement forces the customer through more than £100 of betting per £10 of bonus. Mixed-product promotions — an offer that requires gambling on two or more product types, such as “bet on football to get free spins” — are banned. A free bet whose stake is not returned with a win sits outside the cap where no wagering condition attaches, and the open question is whether the Commission will treat them in the same way. The bookmaker’s headline “100% bonus” is a smaller claim today than it was a year ago, and that is the rule doing its quiet work.
Help exists, and it is independent of the operator. GamCare runs the National Gambling Helpline, GambleAware funds treatment and research through the operators’ voluntary levy, the NHS runs gambling clinics, and Gamblers Anonymous runs peer meetings. Unibet’s safer-gambling block links to BeGambleAware, GamCare, GAMSTOP, Gambling Therapy and the Betting and Gaming Council — a reasonable template for any licensed site, and a useful list to keep open if the operator’s own controls fail to hold.
The legal and consumer-protection frame does not tell a reader how to win. It tells them which operators are accountable for the bets they take, and which protections follow the licence the next time a welcome offer walks past their eye. The mobile frame, which is where most of those bets will be placed, sits directly on top of it.
Today’s prediction in the pocket: what mobile changes
Most of the bets this page discusses are placed on a phone. That sounds like a fact about hardware, but it shapes how a “prediction” lands. A tipster’s email arrives in the morning, the price on offer moves inside the bookmaker’s app before the reader has finished reading the analysis, and the bet is placed with a swipe. The temporal compression is the point — and it has consequences for both the value of a tip and the cost of an impulse.
Prediction apps split into three rough layers. The first is a tipster service that delivers lines or selections by notification, usually on a subscription. The second is a model or stat service that publishes probability estimates and lets the reader compare them to the bookmaker’s price. The third is the bookmaker’s own app, where the price is published and the bet is placed. The licensed bookmakers reviewed below all publish apps with the third feature — Sky Bet, Paddy Power, Betfair, William Hill, BetVictor, Unibet, Coral — and most layer the second on top with player stats, acca statistics and form guides. The first layer, the outside tip, sits somewhere outside the bettor’s account, and the second and third are joined at the hip because the bookmaker wants the bettor in-app.
The Vbet app is published by SCGO Limited and bundles pre-match and in-play betting, Bet Builder, live streaming and a live calendar with results and stats — a full spectrum of the second and third layers. Paddy Power’s app layers Bet Builder+, Popular Bet Builders, Super Sub (a feature that rolls a player bet over to their replacement if substituted), expanded Win More markets and acca and player statistics. bet365’s app is built around in-play markets and live streaming across events worldwide, with Bet Track, Match Live and a Live Golf Tracker for following bets after placement. Each of these reads as a “prediction” tool if the bettor uses it as one — the in-play tracker gives a sense of how a match is moving; the stats give a sense of form; the Bet Builder prices an opinion the bettor has constructed themselves.
The mobile interface also exposes the price moves the desktop hides. Most licensed apps show the latest price prominently, and a tap on the markets panel pulls the older prices away. The reader who wants the time of a price shift has to refresh deliberately. The habit that follows from this is to compare the same selection’s price across apps before placing — a five-minute check across three apps can pull a price in by 0.05 or 0.10 in decimal terms, and on a long-odds selection that adds a meaningful amount to the return. Off-the-shelf tipster services take no account of this; a tip without a price is half a tip.
The handset also makes the cost of betting uncomfortably visible. The bet is one tap from the phone’s banking app; the deposit is one tap from a card already loaded. That convenience is the marketing case for betting apps in the first place, and it is the case the betting limits and deposit-limit toggles in licensed apps are built to interrupt. The reader who sets a deposit limit on the operator’s site will find it applied inside the app at the same point.
What mobile does not solve is the prediction itself. The same maths that governs the desktop market governs the in-app market: the bookmaker’s margin, the probability estimate, the value calculation. The handset changes only the reader’s physical relation to the bet — the calculation hasn’t moved. The next section gives it the rigour the marketing pages do not.
The arithmetic of a prediction: from a tip to a value bet
A prediction is a probability estimate. It is never a certainty claim, and it is the first thing a serious reader holds against a “best bet” pitch. The tipster who says “this team is a banker” is selling certainty the maths does not support; the tipster who says “this team has roughly a 60% chance of winning, and the price being offered is above 1.67” is selling a value bet. The two claims look similar to the eye and behave very differently to the wallet.
Value, in its working form, is simple. A bet has value when the price on offer exceeds the decimal odds that correspond to the bettor’s probability estimate. If the bettor’s model puts the home side at a 55% chance of winning, then the fair price is 1 ÷ 0.55 = 1.82, and any bookmaker’s price above 1.82 has value in the bettor’s favour. A price below 1.82 has negative value even if the home side wins — the bet will return less in the long run than the bettor’s stake was worth at the moment of placement. A reader who treats a tip as a probability estimate first and a name second reads the market with the math intact.
The most popular horse-racing and football markets — match result, both teams to score, over/under, each-way — are priced around two-way or three-way outcomes, and the margin each bookmaker carries is the gap between 100% and the implied probability of all outcomes summed. A two-way market priced at 1.90 / 1.90 implies a payout share of 1 ÷ (1/1.90 + 1/1.90) = 0.95, which is a margin of 0.05, or 5%. That 5% is what the bookmaker keeps on every pound staked, before any cost, any offer, any loyalty scheme. The math gives a number, not a slogan: a bettor who places a hundred £1 bets on this market at the published price gives back £95 of stake and keeps £95 of winnings, leaving the bookmaker with a £5 hold. Three-way markets run higher — Premier League 1X2 typically prices in at 6%-8% margin — and outright markets with longshot runners price in significantly higher still. The margin is the price of admission the bettor pays for the chance of any return at all.
The math behind this carries the recipe page through its worked example. A two-way market at decimal odds 1.90 / 1.90 implies a payout share of about 95% and a margin of about 5%; stated as a band because every actual market in the wild sits somewhere on this scale, the margin is the most useful figure the bettor will ever see and the one the bookmaker is least eager to publish. The bare odds line is a billboard; the margin is the rent.
A practical exercise turns the math into a check the reader can run before any bet. Three pieces of information do the work: the book’s price, the bettor’s probability estimate, and the market’s margin. Convert the price to an implied probability (1 ÷ decimal odds), subtract the margin, and compare what remains to the bettor’s estimate. If the bettor’s estimate of the home side winning is 55%, and the price is 1.83, the implied probability is 1 ÷ 1.83 = 54.6% before margin; after stripping an estimated 5% margin it is 49.6%, which is below the bettor’s 55% — value positive. The same math runs back the other way on a price of 1.95 with the same bettor’s estimate. A pair of figures from the bettor’s own reasoning is the difference between a value bet and a marketing bet.
The bankroll frame is what stops the math from working the bettor into the ground. Staking is the discipline that takes a probabilistic edge and turns it into a long-run gain. The classic rule — a fixed percentage of the bank on every bet, the same unit regardless of how “confident” the bettor feels — is not sophisticated but it is the only rule that matches the math. Confidence is a feeling; the underlying probability is a number; sizing on feeling over-weights the bets that win rarely and under-weights the bets that win often, which kills the edge the math had. The Two-Way On Any Given Day rule: stake 1%-2% of the bank on every bet, no exceptions, and stop when the bank is gone.
Tips fail on three predictable fronts. First, the tip is offered after a market has moved and the price no longer exists — a “best bet” in a tipster feed that names the favourite and reads “back them” is half a tip if the favourite has already shortened. Second, the tip ignores the bookmaker’s margin entirely, naming a winner without naming a price, which gives the bettor nothing actionable. Third, the tip layers in a confidence rating (“five-star certainty”) that the math does not support, and the bettor oversizes the bet to match the rating rather than the edge. A tip worth reading names the selection, names the price window, names the probability estimate, and asks the bettor to size accordingly. Anything shorter is marketing.
Free bets sit inside this frame as a separate kind of offer, and they have their own math. A free bet whose stake is not paid back on a win — the standard arrangement — has a real value of stake × (odds − 1) ÷ odds × payout share of the market being priced, where payout share is the inverse of one plus the margin. A £10 free bet at 3.00 on a market with a 95% payout share is worth £10 × 2.00 ÷ 3.00 × 0.95 = £6.33 on average, not £30 and not £20. The headline value of a “free bet” is the upper bound of what it could win with no margin and no competition; the average value is what the bettor can plan against. Comparing a free bet at 3.00 to a free bet at 5.00 on different books, with the same £10 stake and the same 95% payout share, gives £6.33 versus £12.67 of average value — the higher price earns the offer more even though both are labelled “free bet”.
The wagering requirement on a bonus has its own cost. A £10 bonus with a 10x wagering requirement, played entirely on a 95% payout share market at flat stakes, requires £100 of qualifying bets before the bonus funds can be withdrawn. The expected cost of clearing is the turnover, £100, multiplied by the margin, 5%, giving an expected cost of £5 — half the bonus amount. Two factors can swing the cost: the minimum price rule (a £10 free bet usable only at odds of 1.50 or higher cuts the qualifying markets down and the average edge drops), and the deadline (a 7-day window compresses the number of bets that can be sized defensively). The math does not care whether the bettor sees the cost as “free” in marketing terms; it sees the turnover and the margin.
The worked example above sits at the centre of the section on stakes and value. Two decimal prices for two outcomes of one market; one implied payout share and one implied margin. The reader can re-use the same line of arithmetic on the next market they look at, swapping out the numbers but not the structure. That portability is the point — the next ten operators are about how the market is dressed up; the math is constant.
Staking for a punter is not glamorous. A reader who internalises the relationship between price, probability and margin sees every “best bet” tipster pitch for what it is. The ten-operator ranking below builds on the math, not against it.
The ten UK-licensed bookmakers ranked for today’s prediction
The ten brands below carry a Gambling Commission remote licence for real-event general betting. Each entry names what sets the brand apart in the comparison for today’s tip and offers from a price-discovery angle, rather than naming a favourite. Where one feature helps a prediction-minded bettor more than another, that line is stated. The order is research-driven and not a buy-list.
The single table for this section sets out the licence number, the licence holder, and the operator’s own statement on the key subject.
| Brand | Licence holder and account | The key the marketing leads with |
|---|---|---|
| VBet | SCGO Limited · account 44662 | In-play and Bet Builder inside a single app, with live streaming |
| DragonBet | DragonBet Ltd · account 64908 | Cash out (in-play and pre-match) and racing live-streamed in-app |
| Star Sports | Star Racing Limited · account 9177 | Self-styled UK independent bookmaker with virtuals and casino alongside sports |
| Sky Bet | SBG Sports Limited · account 67370 | Welcome offer of £30 in free bets after a £5+ first bet at minimum odds of 1/1 |
| NetBet | Netbet Enterprises Limited · account 39170 | Daily Boosts, Profit Boosts and a Bet Builder with instant dynamic odds |
| Paddy Power | PPB Counterparty Services Limited · account 39439 | Bet Builder+, Super Sub and acca and player stats across football and racing |
| Fitzwilliam Sports | SBKI Limited · account 48760 | Phone and live chat with the office open 09:00–21:00 every day |
| BetTom | Bet Tom Limited · account 64959 | 50% back as a free bet up to £50 alongside matched casino free funds |
| Spreadex | Spreadex Limited · account 8835 | Combined fixed-odds and spread betting under one roof, both regulated |
| QuinnBet | QuinnBet (Gibraltar) Limited · account 61011 | Free bets usable on any market at 1/2+ with a 50/1 cap |
A few details carry across the table to the sections below. The free-bet rules, the minimum-price requirements, the bonus cap structure and the live-streaming rules. None of these details is uniform across the ten; all of them sit on the operator’s own page and should be checked before any offer is claimed.
VBet
VBet combines Bet Builder, pre-match and in-play markets, live streaming and a results-and-stats calendar inside a single app — the kit that turns a daily tip into something the bettor can actually price. The licence runs through SCGO Limited, and the Commission account is 44662. The bookmaker carries an in-play depth that fits readers who want to act on a tip while the market is moving. The trade-off for newer brands is the welcome-offer scale: VBet is not the £30 or £40 free-bet book, and the offer it does carry carries smaller headlines.
DragonBet
DragonBet offers cash out, both in-play and pre-match, plus live streaming of racing inside the app — a useful pair for the reader whose tip has moved since the morning. The licence sits with DragonBet Ltd on Commission account 64908. Racing live-streaming is the headline feature here, and on a Saturday tip the value is direct. The brand’s profile names smaller and less-trafficked sports than the major bookmakers, so for Premier League-only readers the football depth is narrower.
Star Sports
Star Sports describes itself as the UK’s leading independent bookmaker, with a sportsbook alongside virtuals, casino and live casino. The licence holder is Star Racing Limited, with Commission account 9177. The “independent” label is one of the few genuine distinctions in a market dominated by the merged houses — readers looking for a brand that has not been absorbed into a listed operator group have a smaller but real pool. The second side of the same coin is marketing reach: an independent bookmaker spends less on Premier League sponsorships, and the price-discovery depth on major football is correspondingly narrower.
Sky Bet
Sky Bet’s welcome offer for new customers is £30 in free bets, credited as three £10 free-bet tokens after a deposit of at least £5 and a first single or each-way bet of at least 5p at odds of 1/1 or greater. The brand sits inside SBG Sports Limited on Commission account 67370. The price-discovery depth on Premier League and Championship football is among the largest on the GB register, and the in-play markets run deep enough to service a tip that needs cross-checking across bookmakers. The trade-off is the standardisation of the welcome offer across the SBG group — the headline price is the same shape readers have seen before, and the free-bet math is the same too.
NetBet
NetBet offers Daily Boosts, Profit Boosts and free bet offers, a Bet Builder with instant dynamic odds and sports statistics for major leagues. The licence runs through Netbet Enterprises Limited on Commission account 39170. The Profit Boost frame is the feature that pays a reader’s attention: a boosted price on selected markets each day gives a chance to capture a value bet on a price the bookmaker has inflated. The downside is concentration — Boosts change daily and the markets they touch are limited, so the betting budget that fits the Boost is the daily habit, not the standing account.
Paddy Power
Paddy Power’s app offers Bet Builder+, Popular Bet Builders, the Super Sub feature (a bet that rolls over to the replacement if a selected player is substituted), expanded Win More markets and player and ACCA stats. The licence sits with PPB Counterparty Services Limited on Commission account 39439. The Super Sub feature is the genuine differentiator — it does what no other bookmaker does in the same terms, and the bettor who backs a player market and watches the teamsheet gain a small insurance. The wider group picture matters here: Paddy Power and Betfair run as one licensee in some countries, and the joint depth of football and racing data is what makes either of them worth the install.
Fitzwilliam Sports
Fitzwilliam Sports offers phone and live chat with the office open 09:00 to 21:00, Monday to Sunday, and messenger replies generally within 90 seconds. The licence holder is SBKI Limited on Commission account 48760. The customer-service frame is the brand’s distinguishing feature — a phone call answered in seconds is a service line that the digital-only houses do not match. The market depth is narrower than the major houses, so for the reader whose tip is on a niche market (trotting, lower-league football, women’s tennis) the bet is likelier to need a phone call rather than a click.
BetTom
BetTom’s sports welcome offer is 50% back as a free bet up to £50, with a matching 50% back up to £50 as free slot funds for casino play; full terms apply. The licence holder is Bet Tom Limited on Commission account 64959. The structure is the standard matched sports and casino package, and the value depends entirely on the qualifying bet’s market and price. A £50 free bet on a 95% payout share market at 3.00 average prices around £31.67; a matched casino free-bet package is a separate question about slot RTP and wagering. The bet is two offers in one, and the reader who values one only should look elsewhere.
Spreadex
Spreadex is regulated by the Financial Conduct Authority for spread betting and by the Gambling Commission for fixed-odds betting, and its own page states that financial spread betting losses can exceed the deposit. The licence holder is Spreadex Limited on Commission account 8835. Spreadex’s new customer offer is £60 in free bets for a £10 fixed-odds bet, with the free bets usable across fixed odds and spread betting; the qualifying bet must be placed within 28 days of opening the account. The combined product is the rare feature here — readers who already understand a financial spread bet can move between the two without changing platforms; readers who do not should not start with the spread side.
QuinnBet
QuinnBet free bets are valid for 7 days from credit and can be used on any market at odds of 1/2 (1.5) or greater, with maximum odds of 50/1; straight accumulators are allowed but Trixies, Patents and Yankees are not. The licence holder is QuinnBet (Gibraltar) Limited on Commission account 61011. The combination-flex free-bet rules are useful for the reader whose daily accumulator is the bet they want to place — single bets get no benefit from the combination ban, but a Trixie-style punt is not allowed on the free-bet stake. The 7-day window compresses everything, so a free bet accepted on Monday reads as 168 hours of work by next Sunday.
The ten operators above share the GB licence, the GAMSTOP coverage and the 10x bonus cap. They differ on in-play depth, free-bet terms, market range, app capabilities and the customer-service frame. The math that sits on top of the difference is the same.
What a prediction page actually is, and what it is not
The phrase “best bet prediction for today” carries two unspoken promises. The first is that someone, somewhere, has today’s outcome correctly priced. The second is that a free tip is worth more than a paid tip. Neither holds up to the math or the licensing frame already covered.
A prediction at its useful level is a probability estimate. Any source — a bookmaker’s market, a model, a tipster — that gives a price on an outcome gives an implied probability the reader can compare to their own. The free tip in a Twitter thread is no different in kind from the paid model run: both packages translate a probability into a selection and ask the reader to size accordingly. Where the free tip has fallen behind is in the second step: most free-tip sources do not name the price window, so the bettor has no way to tell whether the tip is still actionable by the time it is read. A free tip a bettor can price and compare is more useful than a paid tip that gives no price at all.
The paid-tip market has its own failures. A subscription model does not require the seller to be right more often than a fair coin — it only requires the bettor to keep paying. The marketing page for a paid tip reads exactly like the marketing page for a paid offer: a few recent winners on the front, the losing ones buried in the archive. The reader who pays for a tip without running the same probability check they would run on a free tip is paying for the marketing, not the math.
The reader’s working question is what probability estimate they have of the outcome and at what price the bookmaker is offering it. Everything else is overhead. The ten operators above offer ten different price-discovery experiences, and the one the reader chooses depends on their preferred betting markets and how they like to size up a tip. The same bookmaker that suits a horse-racing each-way bettor does not suit a Premier League in-play bettor, and the comparison the table above runs is the right shape for that choice.
A book cannot give today’s winner. A page that promises one is not a guide; it is a marketing channel. This page’s frame is to read the marketing on its own terms and walk the reader through the math that does not need anyone’s promise to work. That is what a prediction page is for.
The cost the marketing never names
The marketing across licensed bookmakers converges on three words: “free”, “boosted”, “best”. A free bet is not free in the full sense; it is a stake the bettor accepts without a corresponding deposit and that rarely comes back with the win. A boosted price is a price inflated from the bookmaker’s own line, and the inflation is paid in widened spread or in eligibility rules. “Best odds” is a claim that can only be checked by comparing every other bookmaker’s price on the same selection, and the result is rarely as clear as the ad.
The cost each offer imposes is calculable in pound terms and is rarely stated in pound terms. A £30 free-bet package at 10x wagering on a 95% market is worth £30 of expected bonus minus £15 of expected wagering cost, leaving about £15 of expected value before any qualifying deposit. A 50% back-as-free-bet sports welcome package worth up to £50 carries the same math doubled on the upper bound — £50 of bonus minus £25 of expected cost, leaving £25 of expected value. A daily Boost on a single market at 3.00 priced normally at 2.50 gives 0.50 in extra decimal terms; a £10 stake returns £30 instead of £25, a £5 gain per bet. None of these numbers is large in absolute terms; all of them sit on top of a margin the bookmaker keeps from the underlying price, and the cumulative cost of chasing all of them is what the marketing never names.
The cost the bettor pays for the marketing is not the offer. It is the decisions the marketing moves the bettor into: the bet placed to clear the wagering, the market chosen because the boost limits it, the accumulator stretched to four legs because the free bet allows combination. The offers are profitable to the houses precisely because they ask the bettor to move from the value bet to the conversion bet, and the conversion bet carries the bookmaker’s margin. The reader’s frame for deciding whether an offer is worth taking is the same frame that decides whether a tip is worth taking: subtract the margin, compare the result to the bettor’s own probability estimate, and walk away when the offer sets the comparison below zero.
The reader who runs that frame through every offer and tip walks out with a bookmaker’s profit on the bets the math loses and a bookmaker’s margin on every winning bet, which is the long-run cost the marketing never names. The reader’s working defence is the same defence as at the start: the math is portable, the offers are local, and the bettor who treats the offer as one piece of information among several is the bettor who stays in control of the cost.
The mechanics of a value bet, step by step
The worked arithmetic this page carries is the recipe the reader is meant to run. Two-way market at decimal odds 1.90 / 1.90, taken as an example because it lets the payout share and the margin strip out cleanly. The implied probability of one outcome at 1.90 is 1 ÷ 1.90 = 52.63%, and the two probabilities sum to 105.26%, above 100% by 5.26%. The payout share is 1 ÷ 1.0526 = 95%, and the margin is the residual of 5%. Every two-way market sits on this scale, with the precise margin varying from bookmaker to bookmaker and market to market.
The first step is to convert the price to an implied probability and subtract an estimate of the margin. The bettor’s own probability estimate of the outcome is then compared to the post-margin probability. A bet at 1.90 on an outcome the bettor puts at a 55% probability gives 1 ÷ 1.90 = 52.63% pre-margin, an estimated 47.37% post-margin on a 5% margin, and 55% > 47.37% — value positive by 7.63 percentage points. The same bet on the same outcome at 1.83 gives 1 ÷ 1.83 = 54.6% pre-margin, 49.6% post-margin, and 55% > 49.6% — value positive by 5.4 points. A bet at 1.70 gives 1 ÷ 1.70 = 58.8% pre-margin, 53.8% post-margin, and 55% > 53.8% — value positive by 1.2 points. The price where value turns negative is somewhere between 1.70 and 1.65; the bettor’s estimate puts it at 1 ÷ 0.55 + a 5% margin, which is 1.82 ÷ 1.05 ≈ 1.73.
Three things follow from this. First, the same estimate can give value at one bookmaker and not at another, and the difference can be 0.10 in decimal terms without anyone moving the line — the discount is the margin. Second, the bettor’s estimate has to be honest, and the only honest estimate is one that has been wrong before and survived the re-pricing. Third, the bettor who treats “value” as a feel rather than a comparison is paying the marketing rather than the math. The reader who runs the math once, on paper, on a tip they already had, sees the calculation; the reader who runs it across a weekend of markets starts to read the bookmaker’s margin as a visible cost, not an invisible one.
The math extends to combination bets the same way. A four-fold accumulator prices each leg by the bookmaker’s individual odds, multiplied together to give the cumulative price. The cumulative price carries the cumulative margin — a four-leg accumulator each with a 5% margin ends with an effective margin of roughly 1 − (0.95^4) = 18.55%, more than three times the single-leg margin. A bettor who treats an each-way double as two independent bets on form rather than a combination on margin is reading the marketing; a bettor who treats the same bet as four marginally-priced legs is reading the math. The accumulator pays the bookmaker several times the margin of a single bet, and that is exactly why operators prize the combination bet.
The math extends to free bets and bonuses the same way. A £10 free bet at 3.00 on a market with a 95% payout share is worth £10 × 2.00 ÷ 3.00 × 0.95 = £6.33 on average. The headline win is £30; the average outcome is £6.33; the gap is what the marketing does not say. A wagering bonus at 10x turnover on a market with a 95% payout share costs the bettor the turnover × the margin = £100 × 5% = £5 of expected loss; the bonus pays £10 and the cost comes out of that bonus; the net is £5 of expected gain before the bettor’s time and staking discipline. None of this is hidden; all of it is on the operator’s own page in different language.
The reader who has read this far is the reader who can read the next offer without the operator’s help. The ten-bookmaker comparison above is the second half of the work; the math is the first.
How the page checks the operator
Every brand that appears on this page holds a Gambling Commission remote licence for real-event general betting. The licence numbers named in the section above are the numbers the Commission’s public register shows on the date the page was compiled. Two checks the reader can run themselves:
- the licence account number named on the operator’s own page should match the register;
- the licence holder named on the operator’s own page should match the registered company at the Commission.
A mismatch is a flag, not a verdict. The Commission sometimes operates multiple trading names under one licensee, so Vbet and QuinnBet and others running under different trade names is not in itself a problem. The reader who sees a licence number on the operator’s page that does not appear on the register is looking at a page that should be checked before a deposit goes in. The page does not provide a definitive test, because the licence number alone proves nothing — the licence holder and the Commission’s register are the proof, and that is the work the page is built to document.
Where an operator’s own statement on a feature is given in the table above, the statement is the operator’s own text — a feature like “free bets valid for 7 days” is what the operator’s help page says about its own free bets. Two operators with the same rule phrased in slightly different ways is the same rule in different words; the register, and not the language, is what makes the rule real.
A second observation: every GB-licensed online operator reviewed on this page is a GAMSTOP member by virtue of the licence condition that has been in force since 31 March 2020. The reader who self-excludes through GAMSTOP is excluded from all of them. The reader who self-excludes through one operator’s own self-exclusion tool is excluded only from that operator; the GAMSTOP route is the one that actually closes the off-ramp. The next section makes the responsible-gambling frame explicit.
Staying in control of today’s bet
A guide to predictions that does not address what happens when a bet goes wrong has stopped halfway. The page is built around probability and value because those are the work, and the work stops for the reader when the math no longer fits their position. The phone has the deposit limit, the time-out, the product restriction and the self-exclusion all in the same settings pane; the Commission’s GAMSTOP web sign-up is the multi-operator route; the help organisations sit one tap beyond the operator’s own links.
The reader who runs a value-bet frame and finds themselves chasing losses to clear a bonus is the reader who should stop. The reader who reads a tipster every morning because the alternative is a quiet inbox is the reader who should subscribe less and walk more. The reader whose betting budget is rent is the reader whose bookmaker’s app should not be on the home screen. None of those sentences is a tipster’s pitch; each is a reflection on what the math actually requires to run for the period the reader cares about.
The next section answers the questions the body has left open.
Frequently asked questions
How do prediction markets work?
Prediction markets are exchanges on which individuals buy and sell shares priced between 0 and 1, where the closing price is a probability estimate of an event. They are not the same as a bookmaker’s fixed-odds market, because the price moves with trading; they sit under a separate “betting intermediary” licence category at the Gambling Commission. A reader who backs a 0.40 outcome and wins £1 a share keeps £0.40 a share on a £0.60 cost, and the exchange takes a small commission on net winnings.
What does 12 mean in betting prediction?
In football match-result markets, “12” is a code for backing either the home side to win (the “1”) or the away side to win (the “2”), with the draw removed entirely. It is a two-way bet on a three-way outcome, and the price is calculated by removing the draw from the bookmaker’s margin. The selection has the same math as any two-way price: implied probability, margin, value comparison.
How do you win at bet prediction?
You do not. What a prediction discipline can deliver is a frame in which value bets are placed more often than not, the bankroll is sized so that losing runs do not break the bank, and the offers and bonuses are taken only when the math supports them. A reader who treats prediction as a win-rate target is selling certainty the math does not provide.
What is a value bet, and why is no tip ever certain?
A value bet is a price on offer that exceeds the decimal odds corresponding to the bettor’s probability estimate. The reason no tip is certain is that the bettor’s probability estimate is itself uncertain — every model is wrong sometimes, every form reading is wrong sometimes, every team-sheet reading is wrong sometimes. The price includes the bookmaker’s margin and a reflection of what other bettors think, both of which the bettor cannot see directly.
What is the bookmaker’s margin?
The bookmaker’s margin is the gap between 100% and the sum of implied probabilities of all outcomes of a market, expressed as a percentage of stake. On a two-way market at 1.90 / 1.90 it is about 5%; on a Premier League 1X2 it is typically 6%-8%; on outright markets with longshot runners it can climb well past 10%. The margin is what the bookmaker keeps of every stake, before any offer, bet or loyalty scheme.
How is the return on a bet worked out from the stake and the odds?
The return on a winning single bet is stake × decimal odds; the net profit is stake × (decimal odds − 1). For a four-fold accumulator, the cumulative price is the multiplication of each leg’s price, and the same formula applies. Each leg carries the bookmaker’s margin, and the cumulative margin is wider than the single-leg margin — the math makes the combination bet more expensive than the four singles.
Tips & predictions – Accumulator
Content created by the «Accumulator» team
