
What badminton odds really pay: a 2026 guide for UK bettors
 Available in US
Badminton sits in an odd corner of the British sportsbook. It is one of the few Olympic disciplines that turns over a full calendar of BWF events week after week, yet the menu on most UK-licensed sites is narrower than for football or tennis, and the markets that do appear are priced with a margin that punishes the bettor who treats them as a copy of a match winner’s market. The numbers behind a price matter more here than they do in a sport where five bookmakers all publish something close to the same line, and the gap between a 1.90 and a 1.85 in the head-to-head tells the reader what the bookmaker is keeping of every pound staked.
This page works through that gap, in the order the material supports. The legal frame sets the ground a British bettor stands on. The responsible-gambling frame sets the controls a licensed site has to make available. The offers section looks at what a welcome bonus actually takes from a small-stake bettor. Live betting and cash out follow, then the questions of tips and prediction markets, then the mechanics of bet types and odds, then the tournaments where the market actually trades. The ranking section compares the ten licensed bookmakers that surface badminton odds in Great Britain and shows what each one keeps in its terms. The overview at the close ties the threads together.
Data current as of 26 October 2026 and checked against the Gambling Commission’s public register.
The legal frame around a badminton bet
A badminton bet in Great Britain is a bet between a customer and a licensed operator under the Gambling Act 2005. The Act covers England, Scotland and Wales; Northern Ireland runs on its own older law, and a “Gambling Commission licence” is a GB licence, not a UK-wide one. The Commission, a non-departmental public body sponsored by the Department for Culture, Media and Sport, issues every operating licence and maintains the public register that is the whole test of who holds one. The register is searchable by business name, trading name, domain and account number, and what it shows is what counts. A domain proves nothing on its own: licensed operators use .com and .co.uk interchangeably, and a .co.uk is not, by itself, evidence of a licence.
Since the Gambling (Licensing and Advertising) Act 2014 an operator whose remote facilities are used in Britain needs a Commission licence wherever the operator itself is based. A Curaçao, Maltese or Gibraltar licence does not stand in for a GB one: a brand may hold any foreign licence it likes and still need the GB one to take a British customer’s stake. Sections 33 and 36 of the 2005 Act, as amended, are the provisions that bring the rule into force. Providing gambling facilities in Britain without the licence the Act requires is an offence under section 33 — aimed at the operator, with a maximum on summary conviction of fifty-one weeks’ imprisonment, a fine to level 5, or both, and six months in Scotland.
Licence types matter because they tell the reader what the operator is permitted to do. The categories that matter for a badminton bet are *remote general betting standard (real events)*, which covers the sports menu on a normal online bookmaker, and *remote betting intermediary*, the licence a betting exchange runs under. A brand listed against one of these categories can price badminton. *Remote general betting standard (virtual events)* is the category for computer-generated fixtures and does not, on its own, licence a real-event bettor. Pool betting, which covers horse and dog racing off-course, is a separate licence and a separate tax line.
There is no statutory list of permitted sports or markets. The Commission’s test is whether the operator holds the category of licence the activity falls under and whether its own terms and the Licence Conditions and Codes of Practice allow the bet. In-play betting is offered by GB bookmakers under those licence conditions and the operator’s customer-protection duties; nothing in the Act restricts it. Esports are treated like any other event; virtual events are a separate licence; bets on politics, TV shows and novelty markets are offered and are not, by statute, prohibited. Betting exchanges are licensed as intermediaries and run under their own terms.
A few practical consequences fall out of this. The minimum age is eighteen and the operator must verify name, address and date of birth before a customer can deposit or place a bet, including with a free bet or bonus — that has been a licence condition since 7 May 2019. Anonymous play at a licensed site is not available. The financial vulnerability check that applies to remote betting once a customer’s net deposits exceed £150 in a rolling 30-day window (since 28 February 2025) is a public-record check against bankruptcy or county court judgments, not an income test and not a credit reference check. The financial risk assessments sometimes called “affordability checks” were announced on 7 July 2026 in a staged plan with no published start date.
There is no statutory cap on stakes in sports betting. Operators set their own maximum stakes and may restrict customers individually, and a badminton market on a smaller bookmaker may be capped at a fraction of the cap a football market carries. Spread betting on financial products is regulated by the Financial Conduct Authority, not the Commission, and a financial spread bettor’s losses can exceed deposits; that is a separate licence regime and a separate risk.
Offshore brands that accept British customers without a Commission licence are not legal to provide facilities to, but no offence aimed at a customer who places a bet with one was identified in the framework. What the customer loses is the protection: no GAMSTOP coverage, no Commission complaints route, no approved dispute-resolution body, no British consumer redress if funds are withheld, and the operator is not bound by the 10x bonus cap or the £150 vulnerability check. The Commission’s enforcement is disruption, not blocking: cease-and-desist notices, search-engine referrals, work with registrars, hosts and payment providers. Court-order DNS blocking powers have been, or are about to be, made available; ISP-level blocking is not in operation.
The controls a licensed bookmaker has to offer
GAMSTOP is the national multi-operator online self-exclusion scheme and a mandatory licence condition for online operators since 31 March 2020. Every GB-licensed online brand listed on the public register takes part. Self-exclusion periods are six months, one year, five years, or five years with auto-renewal, and after the minimum period the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps; a betting shop uses a separate service.
A licensed site must offer a gross deposit limit on a fixed time frame — that is the Remote Technical Standard known as RTS 12. The first changes under it have applied since 31 October 2025 and a second phase was postponed to 30 September 2026; whether that second phase is live at the moment of reading is not established and the reader should check the operator’s safer-gambling page. There is no state-set ceiling for deposits or losses: a deposit limit is the customer’s own choice, and the operator has to provide the tool to set it. Timeouts, reality checks, session reminders and the ability to self-exclude beyond GAMSTOP — by direct request to the operator — are all in the same family of controls.
The third-party help lines are open regardless of operator. GamCare runs the National Gambling Helpline. GambleAware funds treatment and education. The NHS runs gambling clinics. Gamblers Anonymous runs peer-support meetings. Several operators on this list — Fitzwilliam Sports, for one — link to all three on their safer-gambling pages.
The practical sequence when a customer reaches a limit looks like this. The first deposit triggers identity verification against name, address and date of birth; until that passes, the account cannot fund a bet. Once verified, the customer can set a deposit limit in the safer-gambling section of the account, and that limit applies immediately. Timeouts, from twenty-four hours to six weeks, are set in the same area. A self-exclusion through GAMSTOP, set on the GAMSTOP site rather than the bookmaker’s, blocks the customer from every GB-licensed online operator for the chosen period and survives the closure of the betting account.
The piece a British bettor most often overlooks is the credit-card ban. Credit cards have been banned for gambling in Great Britain since 14 April 2020, including credit-card-funded payments through an e-wallet. Debit cards and bank-based payments are not covered by that ban. A punter who tries to fund a deposit with a credit card, directly or via PayPal funded by a credit card, will be refused.
What a welcome bonus really takes from a badminton punter
The promotion rules that govern a badminton offer are not the marketing department’s idea of fairness. Since 19 January 2026, wagering requirements on bonuses have been capped at 10x — a £10 bonus at 50x needed £500 of qualifying bets; under the cap, no more than £100 of qualifying bets is required for that same £10. Mixed-product promotions are banned: an offer that asks the customer to gamble on two or more product types, say “bet on football to get free spins”, is no longer a permitted promotion at a GB-licensed brand. Free bets whose stake is not returned on a win are not, in the framework, “wagering-free” in the marketing sense — the customer’s edge on the free bet is the free-bet amount multiplied by odds minus one and divided by those odds, times the payout share of the market the bet is placed on, and that edge is what the operator gives up. The marketing word for this is usually “free”; the arithmetic is something else.
The book’s welcome offers, taken on their own terms, illustrate the spread. Hollywoodbets gives back the stake on a first losing accumulator as a free bet of up to £30: the qualifying bet has to be £10 or more, on three legs or more, at combined odds of 4/1 or greater, settled within seven days, one free bet per customer. The edge on that free bet, on a market whose payout share is around 95%, works out to the free-bet amount multiplied by 0.05 and adjusted for the price — small, but real, and only on the first losing stake. Bet Ahoy’s headline is “Bet £10 & Get £10 in Free Bets”, split into a £5 sports free bet and a £5 acca free bet; the headline price is one-to-one, and the two pieces are separate. Unibet’s offer is “Get £40 in Free Bets when you bet £20”: deposit and place a sports bet of £20 or more at minimum odds of 2.0 (1/1), free bets expire within seven days of issue, new GB customers only, debit card or instant bank transfer. The edge on a £20 free bet at minimum odds of 2.0 on a market whose payout share is 95% is the £20 multiplied by 1.0 divided by 2.0, multiplied by 0.95 — £9.50 of expected value, give or take the exact market. The seven-day expiry is what bites: a punter who leaves the free bet in the account loses the whole edge at the end of the week.
The marketing word that gives the most trouble on a badminton offer is “free bet” itself. A free bet whose stake is not paid back with a win pays the customer odds minus one times the stake on a winning line; the stake is gone. The arithmetic the page works through, in a moment, is what a free bet is worth on average, and that arithmetic is the ceiling on what the offer is worth to a punter. Anything the marketing tells the reader about a “free” amount is qualified by that ceiling.
Live badminton markets and the cost of a cash out
In-play badminton on a GB-licensed site runs under the same licence as the pre-match market. The available in-play menu varies sharply by brand: a bookmaker whose live product is built around football and tennis may carry only the match winner and the next-game winner during a match, and may pull the market during the interval between games. The bigger books carry more legs and more granular markets.
Cash out is a feature the brand offers, not a feature of the bet. The price the brand offers at cash out is its own quote, not the bet’s true price on the market, and the spread between the cash-out quote and the fair price is the operator’s margin on the cash-out. A punter who cashes out a winning accumulator on the third leg of four is taking that spread, not the accumulator’s expected value. On a tightly priced badminton match where the in-play margin is around 6%, the cash-out margin is wider still — a bettor sees a £100 return on a position whose true price, if the remaining legs went in at the listed pre-match price, would be £112 or so, and the difference is what cash out costs.
Live streaming of badminton events sits in the same licence framework as the in-play bet, and not every GB-licensed bookmaker holds streaming rights for BWF events. Where a stream is available, the customer usually has to be logged in and have a positive balance or have placed a bet on the event; the stream is not a stand-alone product.
The bookmaker’s job in-play is to keep the market balanced, and a badminton match where one player runs to a 11-3 first game is the textbook case: the favourite’s odds collapse, the outsider’s price lengthens, and the cash-out quote on a back-the-favourite bettor’s slip moves sharply. The bettor who wants the slip held to the end is taking the operator’s risk that the favourite closes the match, which the operator has already priced into the in-play margin.
Tips, stats and the market for predictions
“Badminton betting tips” is a search phrase attached to a market that is not what the phrase suggests. A tip is a forecast, and a forecast is somebody’s view of who wins. No forecast changes the price the bookmaker publishes: the price already reflects every view the bookmaker has priced in, plus the margin. A bettor who follows a tipster is taking a view on whether the tipster has information the bookmaker has missed, and the long-run record on that question, across every sport, is unfavourable to the bettor. The bookmaker’s margin sits inside every price, and a tip that ignores the margin is a tip that loses to the price even when it picks the winner.
The legitimate use of stats is to read the price, not to replace it. A badminton match where the favourite’s odds are 1.50 and the head-to-head record over the last five meetings is 4-1 in the favourite’s favour is a match where the price has already absorbed the head-to-head; reading the price tells the bettor whether the favourite is overpriced or underpriced relative to that record, and the answer is rarely a confident yes. Bankroll management — staking a fixed percentage of the bank, not chasing losses, keeping a record of every bet — is the part of “strategy” that actually compounds over time. The forecast is the easy half.
Two specific badminton stats move prices. Head-to-head record, weighted by surface and by recency: a player who has won the last four meetings on a slow court is worth a small edge on a similar court, and the market sometimes misses that edge by a tick or two. Recent form: a player returning from injury, or in the first match of a long trip, may be overpriced at the favourite. Both moves are small, and the punter who treats either as a system has over-read what the data is saying.
The legitimate tools for keeping bankroll under control are the same ones the licensed operator offers: a deposit limit, a weekly review of stake size, and the discipline of stopping a session when the plan says stop. None of those is a tip, and none of them changes the price.
How a badminton bet is priced and what the market keeps
The mechanics of a badminton bet are the same as any other fixed-odds bet. The decimal odds are the return per unit staked, including the stake. A £10 stake at decimal odds of 2.40 returns £24, of which £14 is profit. A combination bet multiplies the legs into one price: three legs at 1.80, 2.20 and 1.60 is a single price of 1.80 × 2.20 × 1.60 = 6.336, so a £10 stake returns £63.36 if all three win.
The bookmaker’s margin sits between what the true probabilities would pay and what the price actually pays. A two-way market priced at 1.90 on each side has an implied probability of 1 / 1.90 + 1 / 1.90 = 1.0526 — that is 105.26%, not 100%, and the 5.26% above 100% is the overround, which is one minus the payout share. The payout share is 1 / 1.0526 = 0.9500, or 95.00%, and the margin is 1 − 0.9500 = 5.00%. The bookmaker keeps five pence of every pound staked on this market across the long run.
The illustrative example the page works with is the same: a two-way market at decimal odds 1.90 / 1.90, fractional 9/10 on each side. The implied probability of the two outcomes together is 105.26%; the payout share is 95.00%; the margin is 5.00%. The market pays back £0.95 in winnings per £1 staked across the long run, in round terms. The actual margin on a badminton head-to-head at a typical GB bookmaker moves with the size of the book: a marquee match between two top-ten players may sit at 4-5%; an early-round qualifier may be 7-9% because the book is small. A match-winner market on tennis, by comparison, often sits at 3-4% on a marquee event. The badminton market is, in this sense, a more expensive place to bet than the tennis market.
The margin is what the punter pays for the convenience of a fixed-odds book. The same match on a betting exchange, where the back and lay prices are set by customers and the exchange takes a small commission on net winnings, will typically print a tighter overround because the exchange does not need to build a margin into the price. The trade-off is liquidity: an exchange on a BWF Super 300 event may be one-sided, and the back price on the favourite may move sharply when a punter places a bet, leaving the next customer worse off.
Free bets are priced on the same margin. A free bet whose stake is not returned pays the punter odds minus one times the stake, on average, multiplied by the payout share of the market the bet is placed on. A £10 free bet at decimal odds of 3.00 on a market whose payout share is 95% is worth £10 × (3.00 − 1) / 3.00 × 0.95 = £6.33 on average across the long run. The marketing word is “free £10”; the arithmetic is £6.33. A free bet whose stake is returned with the win is a different product and is worth close to the full stake, less the payout share.
Conversion between fractional and decimal odds is mechanical. A fractional price a/b converts to a decimal price of a / b + 1. The 5/1 in research’s worked example is 5 / 1 + 1 = 6.00 decimal. The 9/10 in the illustrative two-way market is 9 / 10 + 1 = 1.90 decimal. The evens price (1/1) is 2.00 decimal. The odds-on price (anything shorter than 1/1, like 4/6) is 1 / (4/6) + 1 = 1.50 + 1 = 1.67 decimal, which checks against 4 ÷ 6 + 1 = 0.667 + 1 = 1.67.
Tournaments and fixtures: where the badminton market actually trades
Badminton is governed internationally by the Badminton World Federation, founded in 1934 as the International Badminton Federation. The BWF runs the World Tour, the World Championships, the Thomas and Uber Cups, the Sudirman Cup, the World Junior Championships and a long calendar of Super 100, Super 300, Super 500, Super 750 and Super 1000 events. The Olympic badminton tournament is run under BWF rules; badminton has been an official Summer Olympic sport since 1992, with mixed doubles added in 1996.
The men’s team competition is the Thomas Cup; the women’s team competition is the Uber Cup; the mixed-team competition is the Sudirman Cup, which has been held since 1989. The three are held every two years. The All England Open Championships date from 1900 and remain one of the sport’s traditional events; the BWF World Championships date from 1977. A badminton game is played to twenty-one points with rally point scoring, and a match is the best of three games; at 20-20 play continues until one side leads by two, and at 29-29 the next point wins. The five disciplines are men’s singles, women’s singles, men’s doubles, women’s doubles and mixed doubles.
The market consequence of this structure is that badminton odds are most liquid during the BWF World Tour events, the All England Open, the Thomas and Uber Cups, the Sudirman Cup, the World Championships and the Olympic tournament. A GB-licensed bookmaker’s price on a Super 300 event early in the week may move sharply once the draw is known and may tighten as the book builds. A pre-event ante-post price on the tournament winner is available at most brands and carries a wider margin than the match-winner market because the book is small.
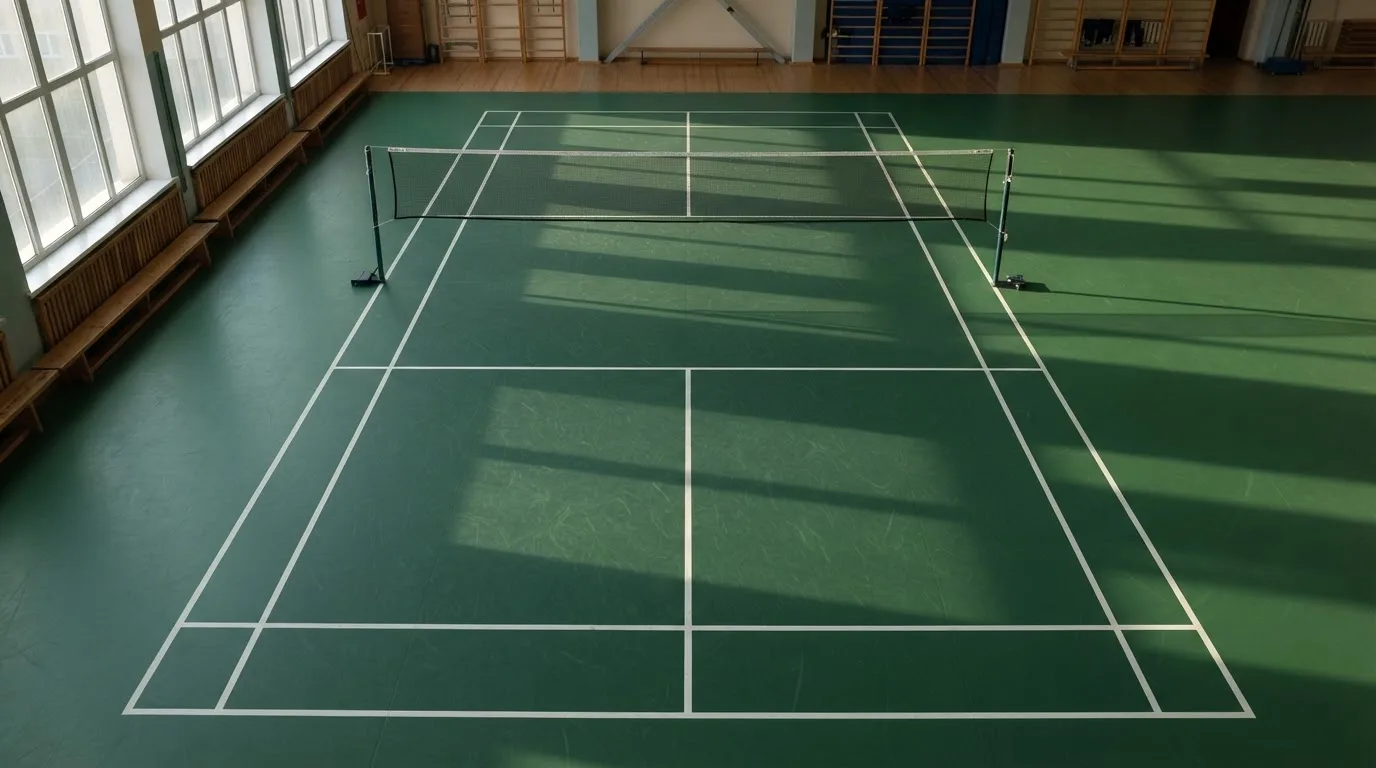
The court itself is fixed: 13.4 m long, 6.1 m wide for doubles and 5.18 m wide for singles, with the net 1.55 m at the edges and 1.524 m at the centre. Those numbers do not move odds, but they explain why a doubles match reads differently in the markets from a singles match and why the surface pace, indoor climate and altitude of a venue can affect the market — and why a bookmaker with a strong in-house data feed on those conditions can hold a small edge over a bookmaker whose data feed is shallower.
The ten licensed bookmakers that surface badminton in Great Britain
The table below covers every GB-licensed operator. The columns are the brand, the Gambling Commission licence number and holder as it appears on the public register, and a one-line summary of what the operator’s own terms state on the subject of badminton odds — what the menu looks like, what the welcome offer takes, what the cash-out and in-play stance is, where the terms carve out an exception. The table is descriptive, not a ranking, and a place in the table is not a licence endorsement.
| Brand | Gambling Commission remote licence number and holder | What the operator’s own terms state on badminton odds |
|---|---|---|
| Ladbrokes | 054743-R-330863-014 (account 54743), held by LC International Limited | Full sports menu on Ladbrokes; the Ladbrokes app in the GB App Store is published by Entain Operations Limited and carries a large football, horse racing and in-play product. Badminton appears in the sports menu under racquet sports alongside tennis and table tennis. The welcome offer on the brand’s sportsbook is governed by Ladbrokes’ own promotions page; the GB App Store rating is 4.66 from 101,255 ratings, which is a popularity marker rather than a payout marker. |
| Bet Ahoy | 100094-R-341742-003 (account 100094), held by Bet Ahoy Ltd | Welcome headline: “Bet £10 & Get £10 in Free Bets”, split into a £5 sports free bet and a £5 acca free bet. The brand is built around the acca market, and the badminton line will be carried where the BWF calendar surfaces a tournament the in-house traders have priced. |
| Fitzwilliam Sports | 048760-R-335434-009 (account 48760), held by SBKI Limited | Describes itself as a Dublin bookmaker with capped membership; the welcome is a “High Stakes Welcome” subject to compliance criteria. Safer-gambling controls include instant deposits, fast withdrawals, timeouts and deposit limits, and the site links to GambleAware, GamStop and Gamblers Anonymous. The membership cap is the unusual feature and shapes which customers the brand suits. |
| London Bet | 066162-R-340278-004 (account 66162), held by Thistle Bet Limited | The London Bet app in the GB App Store combines sports betting — football, tennis, horse racing, greyhounds, darts, golf, cricket, NFL, NBA, MLB and snooker — with Pragmatic Play casino slots and live in-play betting. Badminton is not on the headline sports list the app description carries and would need to be checked on the in-app menu before relying on the brand for a BWF fixture. |
| Unibet | 045322-R-324275-019 (account 45322), held by Platinum Gaming Limited | The brand has operated since 1999; the sports welcome offer is “Get £40 in Free Bets when you bet £20” — deposit and bet £20+ at minimum odds of 2.0 (1/1), free bets expire within seven days, new GB customers, debit card or instant bank transfer. The badminton market sits inside a deep multi-sport menu and the in-play product on tennis and table tennis is the template the badminton in-play product follows. |
| Smarkets | 039173-R-319366-011 (account 39173), held by Smarkets (Malta) Limited | A betting exchange, not a traditional bookmaker; the licence category is remote betting intermediary, not remote general betting standard (real events). UK open-bank deposits are instant from £10 up to £10,000 and withdrawals are processed within six hours from £10 up to £100,000; UK debit-card deposits are instant from £10 up to £15,000. The badminton market, where liquidity exists, runs on back and lay prices set by other customers and the exchange takes a commission on net winnings rather than building a margin into the price. |
| Fafabet | 057385-R-333191-006 (account 57385), held by Taichi Tech Limited | Pays Best Odds Guaranteed on UK and Irish horse racing win and each-way bets from 9am on race days: if the starting price is bigger than the original price, the bigger odds are paid. The Best Odds Guaranteed mechanic is horse-racing specific and does not extend to badminton, but it is the clearest indicator of the brand’s stance on price — and the badminton menu is one of the smaller ones on a multi-sport bookmaker. |
| bet365 | 055148-R-331498-002 (account 55148), held by Hillside (UK Sports) ENC | The official global betting partner of the UEFA Champions League and the most-downloaded sports betting app in the UK by the GB App Store ranking. Carries Bet Builder+ (combining markets from one event pre-match and in-play), Super Boosts, Winnings Boosts on Bet Builders and selected singles, and daily Bet Boosts. The in-play product is one of the deepest in the British market, with live streaming of events worldwide, Bet Track, Match Live and a Live Golf Tracker. The badminton menu sits inside this depth and is one of the broadest on a GB-licensed site. |
| Hollywoodbets | 053028-R-330019-013 (account 53028), held by Hollywoodbets International UK Limited | Sports welcome offer: new players who deposit £10+ by card get their stake back as a free bet of up to £30 on their first qualifying losing accumulator (stake £10+, 3+ legs, combined odds 4/1 or greater, settled within seven days), one free bet per customer. The acca framing is the heart of the offer and the badminton menu is where the brand’s traders have priced a BWF event. |
| Kalooki Sportsbook | 057730-R-333396-005 (account 57730), held by Kalooki Sportsbook Limited | Operated by Kalooki Sports Book Ltd (company number 12938274), licensed by the Gambling Commission under account number 57730, and a GAMSTOP member. The brand’s compliance checks are visible at sign-up and the account-funding flow is the standard GB-licensed one; the badminton menu sits inside the sportsbook product and the size of the in-play menu is the question a bettor answers by checking the in-play product directly. |
The point of the table is not the licence numbers, which the reader can look up on the public register, but the spread across the brands. Three of them (Ladbrokes, bet365, Unibet) carry a deep multi-sport product with badminton as a line item. Two (Bet Ahoy, Hollywoodbets) build their welcome around the acca market and price badminton where the BWF calendar makes it worth pricing. One (Smarkets) is an exchange, and the mechanics are different. One (Fafabet) leads on price for horse racing and carries badminton as a smaller line. One (London Bet) puts badminton somewhere below the headline sports on its app description. One (Fitzwilliam Sports) caps its membership, which makes it a fit for some customers and a non-fit for others. One (Kalooki Sportsbook) is a smaller licensed bookmaker whose badminton menu sits inside its sportsbook product.
The table also marks one brand that does not appear because it does not surface badminton: London Bet. The GB App Store description lists football, tennis, horse racing, greyhounds, darts, golf, cricket, NFL, NBA, MLB and snooker, with badminton absent from the headline list. A bettor who wants a price on a BWF event should check the in-app menu before relying on London Bet as the place to take that price.
The overview: what a badminton bet at a UK-licensed bookmaker actually costs
The picture, taken together, is this. A badminton bet at a GB-licensed bookmaker is a fixed-odds bet between the customer and the operator under the Gambling Act 2005, with a Commission-issued remote licence behind the operator. The customer is verified before the first deposit, is over eighteen, and pays no tax on winnings. The bookmaker’s price carries a margin — somewhere in the band of 5% on a marquee match winner and 7-9% on a smaller book — and that margin is the long-run cost of the convenience of a fixed-odds book over an exchange.
The controls are in place: GAMSTOP self-exclusion, deposit limits, timeouts, the credit-card ban and the £150 net-deposit vulnerability check. The offer the bookmaker publishes is governed by the 19 January 2026 promotion rules — a 10x wagering cap, no mixed-product promotions — and the marketing word “free” on a free bet is qualified by the arithmetic of what the free bet is worth on average at the margin the operator runs. The cash-out quote is the bookmaker’s own price, not the bet’s true price on the market, and the spread between them is the cost of taking the cash out.
The choice of brand is a choice of menu depth, in-play depth, acca framing, exchange mechanics, or membership cap. Three brands (Ladbrokes, bet365, Unibet) sit at the deep end of the menu and the in-play product, with welcome offers that vary in edge and in expiry. Two brands (Bet Ahoy, Hollywoodbets) frame the welcome around accumulators and price badminton as one of several sports on the acca menu. One brand (Smarkets) is an exchange and runs on back and lay prices set by other customers. One brand (Fafabet) leads on horse-racing price and carries badminton as a smaller line. One brand (London Bet) puts badminton below the headline sports in its app description and needs to be checked directly. One brand (Fitzwilliam Sports) caps membership. One brand (Kalooki Sportsbook) is a smaller licensed bookmaker whose menu the bettor checks at sign-up.
The bettor who wants the deepest badminton coverage, the deepest in-play product, and the broadest range of bet types picks bet365; the bettor who wants a wide multi-sport menu with a strong acca product picks Ladbrokes; the bettor who wants a £40 free bet on a £20 qualifying bet at minimum odds of 2.0 picks Unibet and watches the seven-day expiry; the bettor who wants the back-and-lay mechanics of an exchange picks Smarkets; the bettor who wants the acca-framed welcome picks Bet Ahoy or Hollywoodbets; the bettor who wants the membership-capped bookmaker picks Fitzwilliam Sports; the bettor who wants the horse-racing price leader picks Fafabet and treats badminton as a smaller line; the bettor who wants the smaller licensed bookmaker picks Kalooki Sportsbook and checks the menu directly. None of these is the only right answer, and the margin on the badminton market is the cost the reader pays whichever way they go.
Frequently asked questions
How does a bet on badminton actually get placed?
A bet on badminton is a fixed-odds bet between the customer and a GB-licensed bookmaker. The customer opens an account, has name, address and date of birth verified, deposits by debit card or bank transfer (credit cards are banned for gambling in Great Britain since 14 April 2020), picks a BWF event from the sports menu, selects a market — match winner, set winner, handicap, total games — enters a stake, and confirms the bet on the betting slip. A win pays the stake times the decimal odds; a combination bet multiplies the leg prices into one.
How can a bettor check that a bookmaker holds a Gambling Commission licence?
The Commission’s public register is the whole test. Search by business name, trading name, domain or account number, and the register lists the licence category, the licence number and the licence holder. A bookmaker licensed for *remote general betting standard (real events)* can price badminton. A bookmaker licensed for *remote betting intermediary* runs an exchange. A .co.uk domain is not evidence on its own; a brand may use any domain it owns and a foreign licence does not substitute for a GB one.
How is the return on a bet worked out from the stake and the odds?
The return on a winning single is stake multiplied by decimal odds. The net profit is stake multiplied by (odds minus one). On a £10 stake at decimal odds of 2.40 the return is £24 and the profit is £14. On a combination bet the leg prices multiply into one price: three legs at 1.80, 2.20 and 1.60 is 1.80 × 2.20 × 1.60 = 6.336, so a £10 stake returns £63.36 on a win.
What is the bookmaker’s margin and how does it show up in the odds?
The margin is what the bookmaker keeps of every pound staked, on average, across the long run. It is the difference between 100% and the sum of the implied probabilities of the outcomes. A two-way market priced at 1.90 on each side has implied probabilities of 1 / 1.90 + 1 / 1.90 = 105.26%, a payout share of 1 / 1.0526 = 95.00%, and a margin of 5.00%. The bookmaker keeps five pence of every pound staked on that market, in round terms.
How do fractional odds such as 5/1 convert to decimal odds such as 6.00?
A fractional price a/b converts to a decimal price of a / b + 1. The 5/1 example is 5 / 1 + 1 = 6.00 decimal. The 9/10 example is 9 / 10 + 1 = 1.90 decimal. The 1/1 (evens) is 2.00 decimal. The 4/6 (odds-on) is 4 / 6 + 1 = 1.67 decimal.
Which tools for controlling play does a licensed bookmaker have to offer?
A licensed remote bookmaker has to offer GAMSTOP self-exclusion (six months, one year, five years, or five years with auto-renewal), a gross deposit limit on a fixed time frame, timeouts, reality checks and the ability to self-exclude directly with the operator. The credit-card ban is enforced at the payment stage. Help is available through GamCare (National Gambling Helpline), GambleAware, NHS gambling clinics and Gamblers Anonymous, and a licensed operator’s safer-gambling page links to those services.
Tennis, darts & cue sports – Accumulator
Content created by the «Accumulator» team
